The Pound-Rand rate (GBP/ZAR) holds above 22.00 as Crédit Agricole forecasts South African rates staying at 7.25% through Q4, with oil the main risk.
The Pound held on to most of Thursday’s sharp gains against the South African Rand as Crédit Agricole questioned whether investors were expecting too many further South African rate increases.
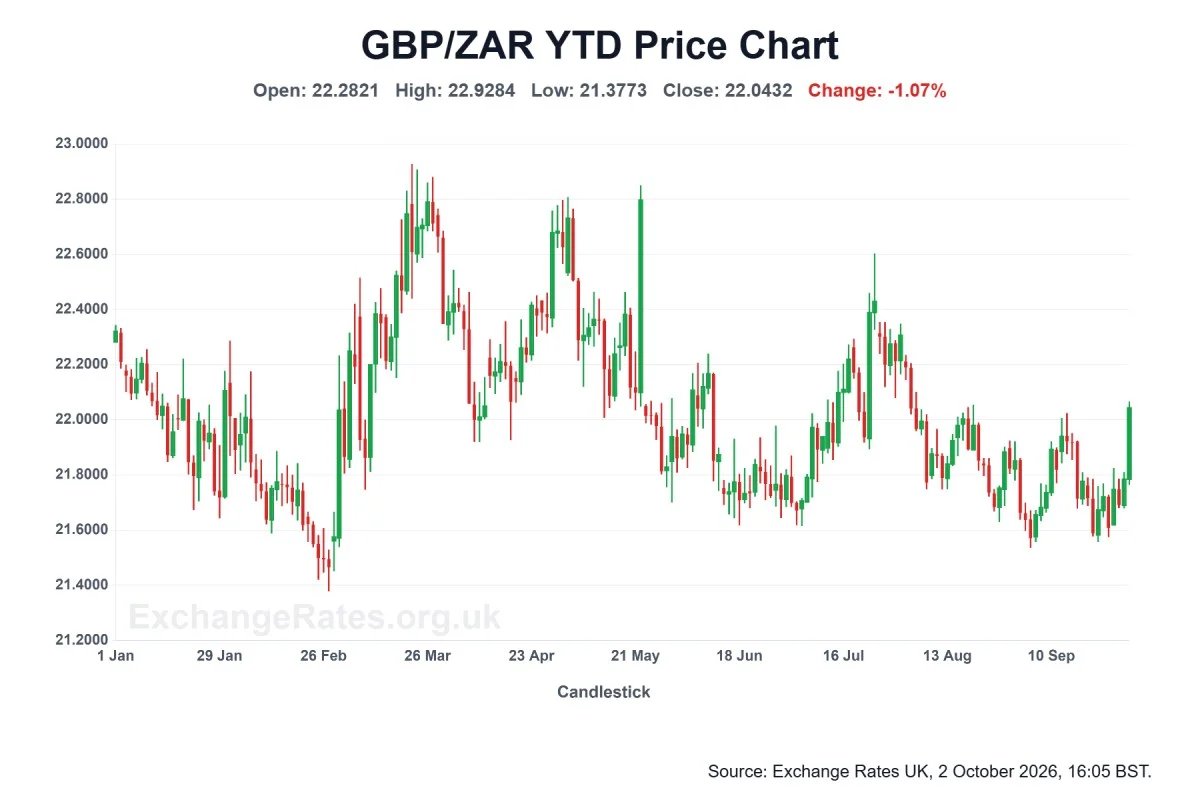
The Pound to Rand exchange rate (GBP/ZAR) traded around 22.0374, down just 0.03% on Friday after climbing 1.19% in the previous session.
That left Sterling above its September closing level of 21.7846, although still below where it began the year.
Crédit Agricole’s argument concerns a potential loss of interest-rate support for the Rand.
In its 30 September research, the bank calculated that markets were pricing another 66 basis points of tightening over six months, following the increase in the South African Reserve Bank’s policy rate to 7.25%.
“According to our calculations, the market currently prices an additional 66bp in the next six months. In our view, this is too much.”
A pause after September’s hike
The SARB’s September decision raised rates by 25 basis points, effective from 25 September, with all committee members supporting the move.
However, its central projection envisaged broadly stable rates for the remainder of the year.
Crédit Agricole sees an important distinction between acknowledging inflation risks and committing to further increases.
“The central bank mentions a base-case scenario (derived from its model) where the policy rate would be kept at 7.25% till the end of the year. In a risk scenario, rates could be hiked: once or twice depending on what oil prices and wages do between now and then.”
Weak activity also argues for caution.
The bank points to a 0.2% quarterly contraction in GDP during Q2 and a 7.9% annual decline in electricity production in July.
“Despite the increase in inflation YTD, the short-term real rates have remained above 2.5%. The central bank will likely weigh the possibility of further hikes against the need to support growth.”
Its analysis finds that the sharp energy-driven acceleration in inflation during April to June subsequently moderated.
“Based on July and August, and assuming that the oil price may moderate in Q4, it would make sense for the SARB to stick to a wait-and-see stance.”
Crédit Agricole therefore retains its forecast for unchanged rates during Q4, with the next decision on 19 November, while acknowledging that renewed oil-price pressure could force a different outcome.
For the near-term GBP to ZAR exchange rate, our reading is that a retreat in South African hike expectations could make it harder for the Rand to reverse Sterling’s latest gains, all else equal.
But that currency implication depends on how UK rate expectations and wider investor sentiment evolve too, while the bank’s hold forecast remains conditional on energy costs easing.
Our currency coverage draws on live market data, official economic releases and published bank research.